
IVCA Secondaries Conference 2026: Industry Leaders Highlight Governance, Transparent Economics and LP-GP Alignment in Continuation Funds

Mumbai : As continuation funds gain traction in India’s evolving secondaries market, questions around governance, valuation transparency, carried interest and investor alignment are becoming increasingly important. These issues were at the centre of discussions at the IVCA Secondaries Conference 2026, hosted by the Indian Venture and Alternate Capital Association (IVCA) in Mumbai, bringing together investors, fund managers and industry experts to examine the opportunities and complexities associated with continuation fund transactions.
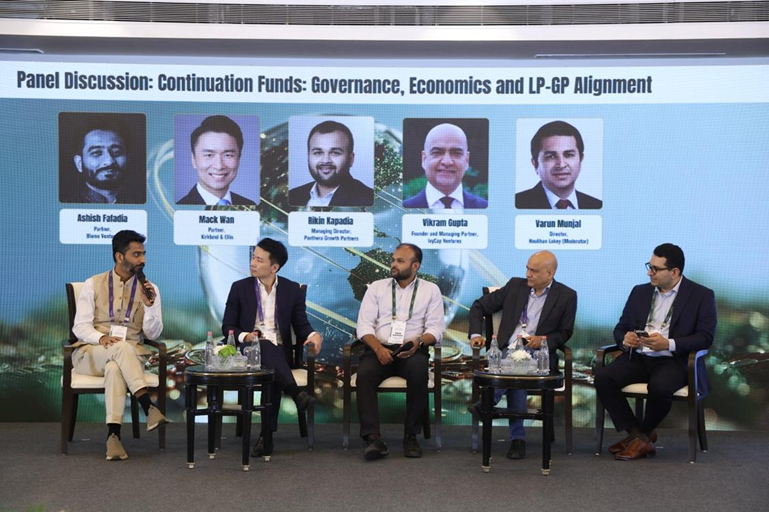
The panel discussion, titled “Continuation Funds: Governance, Economics and LP-GP Alignment,” examined how fund managers can balance the interests of existing limited partners (LPs), incoming investors and general partners (GPs) when transferring portfolio assets into continuation vehicles. The discussion covered the implications of carry resets, taxation, investor approval processes, independent valuations and governance safeguards, with particular emphasis on ensuring transparency and meaningful choices for LPs opting to exit or retain their investments.
The session featured Ashish Fafadia, Partner, Blume Ventures; Mack Wan, Partner, Kirkland & Ellis LLP, Rikin Kapadia, Managing Director, Panthera Growth Partners; Vikram Gupta, Founder and Managing Partner, IvyCap Ventures; The discussion was moderated by Varun Munjal, Director, Houlihan Lokey.
India-focused continuation vehicle transactions have included deals of varying sizes in recent years. At least $1.78 billion in transaction value has been reported across six publicly reported India-focused continuation vehicle transactions with disclosed values, alongside one additional transaction for which the value was not disclosed. Notable transactions include ChrysCapital’s $700 million in 2024, Multiples Alternate Asset Management’s $430 million in 2025, Kedaara Capital’s $300 million in 2025, Samara Capital’s transactions in 2021 and 2023, valued at approximately $305 million combined, and YourNest Venture Capital’s approximately $45 million in 2026. Global participants identified across these transactions include HarbourVest Partners, LGT Capital Partners, Pantheon, Hamilton Lane, TPG NewQuest, TR Capital, and StepStone.
Panellists discussed the implications of crystallising and resetting carried interest on the full asset value in a continuation vehicle, including how the resulting economics affect the sharing of future gains between GPs and limited partners (LPs). The discussion also examined mechanisms such as tiered carry, performance hurdles, co-investment, and reinvestment of crystallised carry to address potential conflicts of interest.
Speaking during the session, Ashish Fafadia, Partner, Blume Ventures, said, “The tax implications of a continuation vehicle cannot be avoided. There is a tax liability for selling LPs when they exit, and GPs also have to pay tax on crystallised carry. In our experience, we have reinvested the net-of-tax carry proceeds across multiple SPVs. The tax impact is around 12.5%, give or take. LPs also ask whether they can generate a 20-25% IRR net of carry.”
The conversation further addressed the choices available to existing LPs when a continuation vehicle is proposed, including the option to sell their interests or roll their investment into the new vehicle. Panellists considered whether election windows provide sufficient time for investors to assess these options and discussed the role of Limited Partner Advisory Committees (LPACs) in reviewing and approving continuation fund transactions under the applicable regulatory framework.
Vikram Gupta, Founder and Managing Partner, IvyCap Ventures, added: “A continuation vehicle requires a detailed approval process, and I believe a minimum 75% supermajority vote is important to ensure LP alignment. Many Indian institutional investors have not yet experienced a full exit cycle and may be unfamiliar with continuation vehicles. Fund managers need to explain the asset selection, valuation discount, incoming investors, transaction structure and tax implications in detail. This process can take three to four months, as LPs also need to follow their internal investment committee processes. Starting early and maintaining transparent communication are essential to securing investor support.”
Also in focus was the importance of clear governance frameworks, transparent disclosures, and robust processes in continuation fund transactions. The panellists emphasised that providing existing LPs with meaningful choices, addressing potential conflicts of interest, and ensuring fair treatment of all stakeholders will be critical to building confidence in continuation vehicles and supporting the growth of India’s secondary market.
The IVCA Secondaries Conference 2026 was supported by 360 ONE Asset, Gaja Capital, and Foundation Private Equity as Gold Partners; Blume and Oister Global as Silver Partners; and Kirkland & Ellis and Price Waterhouse & Co LLP as Knowledge Partners.
****
